Get in touch
-
Mark Thomtonmark.thomton@woodmac.com
+1 630 881 6885 -
Hla Myat Monhla.myatmon@woodmac.com
+65 8533 8860 -
Chris Bobachris.boba@woodmac.com
+44 7408 841129 -
Angélica Juárezangelica.juarez@woodmac.com
+5256 4171 1980
China's CMRG targets greater control over iron ore price discovery
4 minute read
- China’s purchasing power has long shaped iron ore prices, but CMRG aims to influence how they are set
- By integrating procurement, inventory and transaction data, trading platforms and benchmarks, CMRG is building virtual vertical integration without owning mines or replacing traders
- For Japan and other buyers outside China’s system, the risk is becoming a price taker twice over
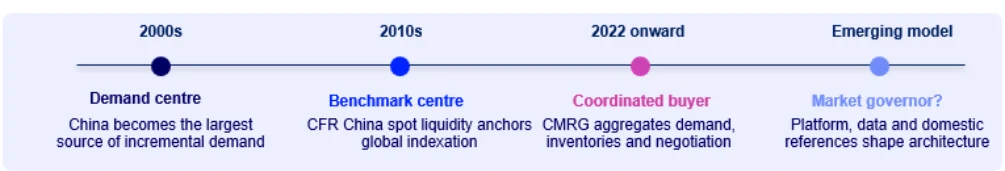
China’s state-backed China Mineral Resources Group (CMRG) is shifting from a centralised purchasing role to a potential force in global iron ore price formation, according to Wood Mackenzie’s latest research. Founded in July 2022 to centralise purchasing, negotiate prices, and manage strategic inventories, CMRG now aims to influence price discovery. It plans to do this by capturing transaction data, steering liquidity, and shaping benchmark references through a state-backed platform.
According to the report, China's CMRG: From Demand Centre to Market Governor, commodity power lies not only in owning mines or controlling physical volumes. It also resides in the ability to decide which transactions are visible, which inventories are accessible, which benchmarks are embedded in contracts, and which participants can intermediate the market. CMRG appears to be assembling all five layers of that capability: purchasing coordination, strategic inventory management, a proprietary trading platform, domestic price indices and long-term contract architecture.
Information as the most valuable asset
Wood Mackenzie notes CMRG's most strategically significant asset as information rather than volume. "By channelling transactions through its own platform, CMRG is gaining greater visibility into mill restocking, cargo rerouting and immediate order flows", says David Cachot, Head of Steel, Iron Ore and Alloys Markets at Wood Mackenzie. "This could also give it a clearer view of whether benchmark prices reflect the transactions that matter most to the market. These are insights that have traditionally been held by miners and international trading houses."
China’s journey from demand dominance to market governance
A looser market strengthens the buyer's hand
CMRG's emergence coincides with a structural shift in iron ore supply fundamentals. New volumes from Guinea and Brazil are arriving as Chinese steel demand matures, creating conditions of marginal surplus. Wood Mackenzie argues that a centralised buyer has considerably more leverage in a market with marginal surplus than in one where mills compete for scarce tonnes, because credible alternatives matter before mills fully exercise them.
The Simandou project reinforces CMRG's position in three ways:
- it diversifies China's supply base
- introduces high-grade blendable material
- deepens China's participation in an important new supply chain
However, the project does not remove dependence on Australia and Brazil, and its ramp-up will be gradual, but it raises the credibility of CMRG's threat to delay, redirect or segment purchases at precisely the moment CMRG is consolidating its negotiating authority.
Japan: secure in tonnes, exposed in architecture
The report identifies Japan's strategic vulnerability. Japanese steelmakers benefit from strong bilateral supplier relationships, well-managed obligations, and support from trading houses with upstream equity, freight, and financing capabilities, which together reduce physical supply risk. However, Wood Mackenzie cautions that Japan could still face price-taking situations on two separate occasions.
"Japanese buyers could continue sourcing from the same miners while their landed cost becomes more sensitive to Chinese port inventories, RMB conditions, domestic sentiment and CMRG's procurement rhythm," Cachot states.
The next contest: green iron units
Wood Mackenzie identifies steelmaking decarbonisation as the next frontier for market governance. As scarcity shifts toward qualified high-grade concentrates, pellets, direct reduced iron feed, and low-carbon metallics, these less liquid, more technically specific markets will depend on long-duration partnerships rather than spot-driven price discovery.
The report states that governance of the green iron supply chain is still evolving. Buyers can strengthen their bargaining position by specifying demand, qualifying feedstocks, co-investing in beneficiation and pelletising, supporting low-carbon ironmaking, and committing to long-term offtake agreements. In this emerging market, the critical asset is not simply iron ore, but ore that is technically qualified, carbon-accounted, pelletised, financed, and delivered for use in low-carbon steel production.
"China spent two decades becoming the indispensable buyer of iron ore," says Cachot. "CMRG suggests that the next ambition is to become indispensable to how the market is organised. The physical market will still impose discipline, but within that envelope, CMRG can influence who sees the market first, who negotiates from a position of patience and who captures the value between benchmark and realised price."